Senior Law Day 2026

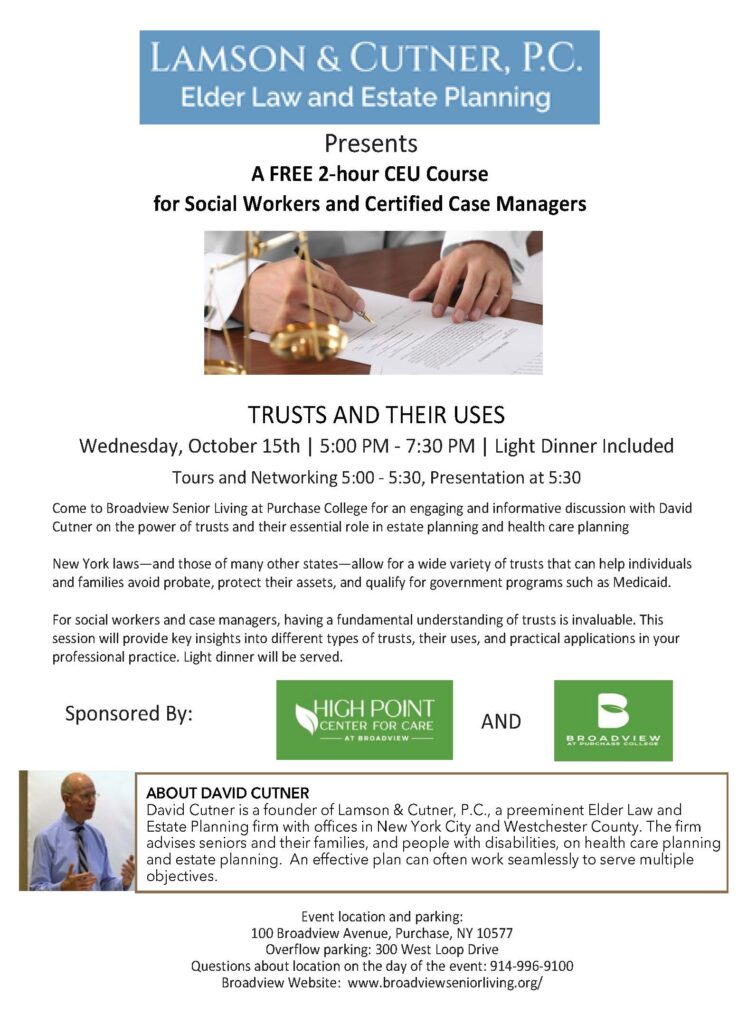
Westchester Senior Law Day will take place on Thursday, October 8.

8:45 am - 2:00 pm at the Westchester County Center, 198 Central Avenue, White Plains, NY.

David Cutner Will Present “Nuts and Bolts of Medicaid Planning” at 11:00 AM in the Main Hall

Senior Law Day 2026, an important annual community event, is free.  It is geared toward older adults who live in New York, in or near Westchester County.  The event includes numerous workshops on legal and financial topics of interest to seniors and their caregivers.  These topics are beneficial in particular to people who need (or may soon need) long-term care.

Professionals attending and presenting include experienced Elder Law attorneys, certified financial planners, geriatric care managers, and Medicare specialists. An important aspect of the event is that a limited number of free 15-minute consultations will be available with these professionals. 

Free parking for this event will be available next to the County Center.

Senior Law Day is a Public/Private Partnership

Westchester County Executive Ken Jenkins said: “We can’t stress enough the importance of planning, especially when it comes to aging. Senior Law Day helps Westchester families navigate legal, financial and health-related concerns. All of us experience these concerns as we grow older.”   The event is hosted in partnership with the Westchester County Department of Senior Programs and Services (DSPS).

Registration and Signup

Advance registration is encouraged, so that event organizers can plan appropriately.  However, walk-ins are also welcome. Register online here, or via the QR code in the flyer below.

Sign-ups for free 15-minute consultations will be available at the event beginning at 8:45 am. The consultations will be with Elder Law attorneys, financial planners, and Medicare/geriatric care managers.

A Trust Is Often the Best Way to Protect Your Home

Trusts are legal structures often used by Elder Law attorneys. Their purpose is to preserve income or assets that you would otherwise be forced to spend on your care. Trusts can be an excellent way to protect your home and preserve your equity. They can shield you from being exposed to Medicaid liens when you no longer live there. They can also shield you from estate recovery.

What happens if you keep the home in your name

Consider you own a house, condominium or cooperative apartment worth $500,000 in today's market. You bought it 40 years ago for $35,000, and your mortgage is paid off. Now you need long-term home care. Your primary residence is an exempt asset for eligibility purposes, but that's not the end of the story. Medicaid may eventually require that some or all of the equity be used to reimburse the cost of your care.

Medicaid can seek to recover their costs in two ways. The first is by placing a lien against your property when you move out permanently. The second is by recovering from your estate via a lien when you die. In both cases, the lien will be equal to the costs that Medicaid incurred for the benefits provided on your behalf.

Long-term care is ruinously expensive. Costs can quickly rise to an amount that would exhaust your entire home equity, should a lien be enforced. Your home equity would be paid to the government to repay the cost of your care. Nothing would be left for your children, loved ones or other heirs.

Why Trusts are so useful

A trust can be used to prevent these unfortunate outcomes. By transferring your home to a trust, you are no longer the legal owner of the home. The home is therefore not subject to a Medicaid lien, or the claims of any other future creditors.

An eldercare attorney can structure a trust to achieve your goals. First, it can allow you to live in your home as long as you wish. A trust can also contain instructions to transfer ownership to your designated beneficiary after you pass.

Keep in mind, if you should require nursing home care within the ensuing five years, the home transfer will be subject to the look back period and could result in a period of Medicaid ineligibility. In this event, other strategies may be available to protect a substantial portion of your home equity.

What is the Medicaid “Look Back,” what is the “Penalty Period,” and how do they work?

Learning about the "look back" and "penalty period" can help you understand more about how Medicaid works.  Here are the rules and the situations in which they are applicable in New York.

First of all:  In New York, there are two categories of Medicaid services:  Community Medicaid and Nursing Home (Institutional) Medicaid.  Community Medicaid covers a wide variety of services, including Home Care and Assisted Living.  Institutional Medicaid covers care in a Nursing Home. Currently the look back and penalty period ONLY apply to Nursing Home Medicaid.

What is the "penalty period" and what is the "look back?"

A “penalty period” is a period of ineligibility that is imposed if a Medicaid Nursing Home applicant has transferred assets during the five (5) years preceding their application. The five years prior to the Medicaid application date are known as the “look back” period. For now, in New York, the “look back” and “penalty period” only apply to Nursing Home Medicaid. 

Community Medicaid and the look back and penalty periods

Currently there is no look back for New York’s Community Medicaid services.  Legislation was passed in 2020 that would impose a look back, but to date it has not been implemented. Whether it will ultimately be implemented is uncertain.

Not having a look back means that there is no Medicaid penalty period if you transfer assets out of your name prior to filing your Community Medicaid application. 

Institutional Medicaid and the look back and penalty periods

Institutional (nursing home) Medicaid works differently.  If you transferred assets out of your name at any time during the five years preceding your Medicaid application, a penalty period will be imposed, during which time you will not be eligible to receive Medicaid benefits.  The period of ineligibility will begin when all of the following are true:

a) You are residing in the nursing home;

b) You have applied for Nursing Home Medicaid; and

c) You would be eligible for Medicaid (because you have only a small amount of money) except for the transfers you made during the five year look back period. 

How the Look Back and Penalty Period work

If you are in a nursing home and apply for Medicaid to pay the nursing home’s bills, Medicaid will first check to see whether you have made any gifts or transfers of your assets during the five years prior to your application date (the “look back period”).   To enable Medicaid to determine whether that is the case, your application will need to include five years of bank records from every single bank account, brokerage account, savings account, or any other institution where you keep or have kept your money during the past five years.  You will also need to include your records concerning real estate, co-ops, life insurance, annuities, and other assets owned during this period.

If you have made any gifts or asset transfers during the look back period, there will be a "penalty." The penalty is that Medicaid will not pay your nursing home costs for a period of time. The length of the penalty period depends on the amount of money you gave away. The number of months that you are not eligible for Medicaid benefits is called the “penalty period.”

How to Calculate the Penalty Period: An Example

Let’s say you live in New York City, and you gave your son or daughter a gift of $150,000 in January 2026. If you need nursing home care at any point up to January 2031, and you file a Medicaid application, your gift would fall within the look back period.

Medicaid would perform a calculation as follows. The amount or value of your gift would be divided by Medicaid’s monthly “Regional Rate.” The amount is set by Medicaid, and the current rate can be found here.  The result represents the period of time in months that you are not eligible for Medicaid nursing home benefits. The Regional Rate applicable to you depends on your county of residence within New York State.

Let's say that the New York City Medicaid Regional Rate at the time you apply is $15,000.  For our example, the calculation is:  $150,000 (the amount of the gift) divided by $15,000, resulting in a “penalty period” of about 10 months.

Remember, the penalty period does not begin until a) you are in the Nursing Home; b) you have submitted a Medicaid application; and c) you are “otherwise eligible” for Medicaid, meaning you have almost no money in your name.  During the penalty period, someone other than you would have to pay for your care. This would probably end up being the person to whom you gave your money in the first place.

The end result is that all the money you gave away, and often even more, would end up being used to pay for your nursing home care. The gift would come to nothing if you do not plan ahead.

Last-minute Planning Can Still Save You Money

Plan ahead, because steps you can take before you need care can make a huge difference in your financial situation later on, especially if you need to enter a nursing home. 

However, if you are “caught” in the look back period, or fear you will be, do not despair!  An Elder Law attorney will likely have a strategy that can save you a significant amount of money even if you have made a gift or transfer.  Don’t let the “look back” and “penalty period” deter you from seeking advice from an experienced eldercare attorney.  Call us today to gain valuable information, as well as invaluable peace of mind.

May is Older Americans Month: Champion your Health AND Plan Ahead

Eating right, staying active and planning for long-term care can maximize your quality of life

Celebrated every May, Older Americans Month is a time to recognize older Americans' contributions, highlight aging trends, and reaffirm commitments to serving older adults in our communities.  It was established by the Administration for Community Living, a US government organization.

This year’s theme, “Champion Your Health,” focuses on prevention, wellness, and personal responsibility as cornerstones of healthy aging. These common-sense recommendations encourage older adults to take an active role in their health. Actions could include advocating for yourself, accessing preventive care, and making informed decisions that support independence.

Taking care of your health often means accessing care in the home

An enormous financial risk arises as people get older, that most don’t recognize until they are in the midst of a crisis.  Once you need care to remain in your home, that care is often – literally - ruinously expensive.  It can wipe out your life’s savings and threaten your ability to remain independent.

The costs often start out as moderate, but quickly mushroom. Often people’s savings are pouring out of their accounts like water out of a fire hose.  One of the best decisions people can make that support independence and avoid financial devastation, is to do long-term care planning.

Learning about long-term care planning is crucial, even if you are currently in good health.  Understanding the opportunities that are available, and that will be appropriate for you if and when you need health care, will empower you to take appropriate action.  Actions you take can enable you to protect yourself and your assets, and to remain at home and independent as long as possible.

How can you take charge of your health at every age?

We can all take action to remain healthy as long as possible.  The list below is not new, but bears reviewing.

Take care of your health, and plan ahead for the day when you may need assistance.  Both are key components for optimizing your health and your quality of life, and for protecting your financial future.

FREE In-Person CEU April 21, 2026

Register for April 21 CEU Course at The Watermark at Brooklyn Heights

This field is for validation purposes and should be left unchanged.

Contact Details

Name(Required)
Professional Designation(Required)

Finalized NY 2026 Medicaid Resource and Income Levels

New York State has published finalized Medicaid thresholds and limits for income and assets for 2026. Some of the figures are based on the Federal Poverty Level (FPL), which the Federal Government publishes in February. Other New York State figures were published at the end of last year. Click on the chart below to print it.

Most of the limits for "resources" (assets) and income increased slightly in 2026, as they normally do each year. For example, to be eligible for Medicaid, in 2026 a applicant who is single can have no more than $33,038 in "countable resources" in their own name, up from $32,396 in 2025. If a single person is receiving Medicaid services in the community, any monthly income over $1,836 is considered "surplus income" in 2026, up from $1,800 in 2025.

The "regional rates" that are used to calculate a penalty period for Institutional (Nursing Home) Medicaid also rose slightly. A penalty period is imposed if a nursing home resident who applies for Nursing Home Medicaid has made an uncompensated transfer (in essence, a gift) during the five years before the application is submitted. The five year period is called the "look back." The length of the penalty period is calculated from the amount of the transfer. Learn more about the look back and penalty period here.

Starting the planning process early can be important and is therefore likely to be in your best interest. If you call our firm, we will review your situation, carefully explain the steps we recommend that you take, and will assist you to execute AND implement your plan.

Call now - (212) 447-8690 or (914) 732-3636, or use our "Contact Us" form to get started!

When You or a Loved One Needs Help: Taking the First Step Can Bring Peace of Mind

The holidays can be joyful, but also sad or anxious.  Those who have family and/or good friends can enjoy spending time with their loved ones, but sometimes seeing someone after time spent apart makes you realize that worrisome changes are occurring, and that your family member or friend needs help. Or perhaps you realize that you are the one who would benefit from some assistance.

The problem is that many people don’t know where to start.  What is needed: a aide, a daily money manager, a geriatric care manager, an eldercare attorney, or something else?  Who should you call?  It can feel overwhelming and depressing.

The answer is usually closer than you think, and surprisingly easy to do.  The best first step is to call a professional who deals with the numerous aspects of aging, and start a conversation. 

You want to ensure that you have considered the best possible choices available to you.  The reason we feel it is best to call an Eldercare or Elder Law attorney (the terms are used interchangeably), is that they know the legal and financial aspects of long-term care planning, and they have connections with many other service and care providers who can help with other aspects of aging.

At our firm, during the initial phone call we will review some of your basic information, and we will recommend the next steps for you.  Often the recommended next step would be a consultation with one of our attorneys, but that is not appropriate or necessary in every situation.   If indicated, we can and do refer people to other organizations that are better able assist them.  We are happy to begin the process of guiding you to the people who are best suited to serving your needs and objectives.

After your phone call, an initial consultation at our firm will involve an in-depth review of your health, family, and financial situation, as well as your personal objectives.  All these aspects of your life feed into the plan an Eldercare attorney will recommend.

The consultation will address the available legal options, but the discussion often reveals additional needs and indicates other services that could be helpful to you.  If you need assistance with other aspects of aging, we can recommend excellent professionals in other fields as well.

For example, if you need an aide in the home, many of the home care agencies you might contact accept private pay only.  While we know and often recommend excellent private pay agencies, you may also want to consider using an agency that accepts Medicaid payment as well as private pay, if you are considering seeking Medicaid benefits. 

If you need another type of service provider, such as a daily money manager or financial advisor, we are happy to refer you to other professionals we know and trust.  We are not paid for referrals, nor do we pay for them.  Everyone’s goal is simply to give excellent service.

This procedure – in-depth consultation, determining your needs and objectives, recommending legal steps and referring other professionals whose services you may need – is how we operate every day.  Not all Elder Law firms work this way.

Feeling that the first call you make will open the door to finding a plan that works for you, and will also provide you with access to other professionals you can trust, can bring tremendous peace of mind.  Call today, then you can relax and actually enjoy the holidays!

5 Reasons a Medicaid Asset Protection Trust is an Essential Planning Strategy

More so in New York than in any other state, Medicaid is not “just for poor people.” Medicaid serves millions of people in New York, many of whom own homes and have investments and savings. They and their families would be devastated financially without Medicaid assistance for their long-term care needs. Once someone needs long-term care, costs can quickly escalate. Money can start to pour out of their bank account with terrifying rapidity, and with no end in sight.


Some mistakenly believe that Medicare will cover their needs.  It will not.  Health or medical insurance does not cover long-term care.  Only long-term care insurance will cover long-term care and very few people have a policy.  And for those who have a policy, often the coverage and benefits are inadequate.

Most people will come face to face with the shocking fact that even a modest amount of home care could cost $100,000 per year, or that assisted living or nursing home care could cost $150,000 to $200,000 per year.  Multiply these numbers by 3, 4, or 10 years of increasing long-term care needs.  Most people don’t have this kind of money to spend without rapidly depleting their life’s savings and jeopardizing the ownership of their home.  And, of course, the fees for these services rise every year.

Fortunately, residents of New York can take steps to avoid financial disaster.  One of the most effective strategies is to create and fund a Medicaid Asset Protection Trust (“MAPT”).  Here are five reasons why the MAPT is so valuable and effective.

1. A  Medicaid Asset Protection Trust will facilitate eligibility for Medicaid

In order to be Medicaid eligible, you can have only a very limited amount of assets in your name.  When you create and fund a MAPT, think of the Trust as another person.  The trust assets no longer belong to you and cannot be counted by Medicaid in determining your eligibility.  Once the amount of your assets is below the eligibility level, you can quickly obtain Community Medicaid benefits, including home care or assisted living care. 

For Community Medicaid, there is an income limit, but your income is NOT a factor in determining Medicaid eligibility.  In fact, if your Medicaid Asset Protection Trust contains investments that produce income, e.g., interest or dividends, you can continue to receive all of the investment income even though you no longer own the underlying assets.  Receipt of this income will not affect your eligibility for Medicaid.  However, you may need to protect your so-called “surplus income” in a different kind of trust, the Pooled Income Trust.

While creating and funding a MAPT will allow you to quickly attain eligibility for Community Medicaid, the path to Medicaid Nursing Home eligibility may take more time due to the five-year “look back.” 

2. A Medicaid Asset Protection Trust helps your money last longer

The goal of the Medicaid Asset Protection Trust is to protect your assets and make them last as long as possible, so that you (and your spouse and family) can maintain a comfortable lifestyle.  You may have a mortgage or other financial obligations or want to modify your home to make it safer and easier to live in as you age, or need to replace appliances, the roof, or fix the plumbing.

While the assets in the MAPT are no longer subject to your control, the Trustee can be given the authority to distribute trust assets to others, typically to a Co-Trustee or other family members.  They can use the assets distributed to them to pay for anything that you may need or want.  When you choose the Trustee(s) and beneficiaries of your Asset Protection Trust, you will want to keep this possibility in mind.

Creating an MAPT is not a “loophole” or an effort to “hide” your money.  Protecting your money and property and attaining eligibility for Medicaid are not improper or unethical goals – they are an optimal outcome.  Medicaid is very well aware of the use of the Medicaid Asset Protection Trust, and will review your trust in the application process.  Elder Law attorneys have been using this strategy for years.

3. Placing your assets in an MAPT protects them from important risks

Most seniors are planning to leave their assets to their children or to other family members.  When they learn that they need to reduce the amount of assets in their own name in order to qualify for Medicaid benefits, the obvious conclusion to many is to give their assets now to their family members.  The recipients of such gifts use these funds to pay for whatever the senior may need or want.  This can be the simplest path to Medicaid eligibility, but it is problematic for a number of reasons:

  1. If the recipient of the gift incurs a debt or liability, what you think of as “your” money will be exposed to a claim by their creditor;
  2. If the recipient of your gift is married and subsequently becomes involved in a  divorce proceeding, “your” assets could wind up in the hands of their spouse;
  3. If the recipient of your gift pre-deceases you, "your" money will be distributed as spart of their estate:
  4. While unsuspected and perhaps unlikely, there is always a possibility that “your” money will misused by the recipient of your gift;
  5. The recipient of your gift will have carry-over basis in the investments and property given to them.  This means that the opportunity to avoid capital gains tax on the appreciation in value of the transferred assets that accrue during your lifetime will be lost.

An Asset Protection Trust can protect your assets from all of these risks, and afford your beneficiaries a “step-up in basis” of appreciated assets, meaning that they will avoid capital gains tax (see below).

4. A Medicaid Asset Protection Trust affords a step-up in basis to its beneficiaries

If you should decide to sell your home or other investments that have appreciated in value over the years, you understand that you may be required to pay capital gains tax.  The tax would be calculated on the amount of the gain, i.e., the difference between the amount you paid for the asset and the net proceeds of sale.  What you paid for the asset is called your “tax basis.”

As stated above, if an asset is gifted during your lifetime, the recipient gets carry-over basis, i.e., the same tax basis that you have.  If the recipient sells that asset, they will pay the same capital gains tax that you would have paid had you sold the asset.  If the asset sold was your primary residence but it did not become their primary residence, they would pay even more tax than you would have paid because they would not qualify for the tax exemption available upon the sale of a primary residence.

However, if your beneficiary inherits the same assets from a Medicaid Asset Protection Trust, the beneficiary receives a step-up in tax basis to the fair market value of the asset as of your date of death.

Here is a hypothetical example:  assume you purchased your home 30 years ago for $100,000.   Upon your death, the home is worth $800,000 and your children want to sell it and divide the proceeds.  If you had transferred ownership to your children during your lifetime, they will pay capital gains tax on the $700,000 increase in value of the home that accrued during your lifetime when the sell the property.  However, if your children had inherited the property from you under your MAPT, they will not pay any capital gains tax on the $700,000 increase in value.

5. A MAPT can serve as your estate plan, and avoid probate

Every Last Will and Testament, without exception, is unenforceable until it is filed with a Probate Petition in the Surrogate’s Court, and the Court determines that it is a valid Will and issues Letters Testamentary to the nominated Executor.  Unfortunately, filing the petition is only the first step.  Potential beneficiaries can demand discovery and  challenge the Will as discussed below.  Even when a Will is uncontested, it can take months (sometimes more) for Letters Testamentary to be issued.  Only at that point does the Executor have the authority to collect the estate assets, pay expenses and creditors, and distribute the remaining assets to the beneficiaries named in the Will. The probate procedure can be expensive, time-consuming, and aggravating.

A Medicaid Asset Protection Trust will similarly contain your wishes and instructions regarding the distribution of the assets that it owns to your beneficiaries named in the Trust.  The distribution of assets from the Trust can be handled privately and without any court involvement at all.  It is a far more efficient – and cost efficient – process than probate, and it avoids all the unknowns, delays, and expenses that come with a court proceeding. 

The MAPT is far better at avoiding disputes regarding the estate than if you have a Will.  Probate rules require that “distributees” (next of kin down to first cousins) be notified of the proceeding.  Distributees are entitled to conduct discovery, i.e., they can require production of relevant documents and information and conduct depositions of witnesses.  They are then entitled to object to the validity of the Will on various grounds, which will result in further delay and expense.  Some cases literally take years to resolve.

When you have a MAPT, however, nobody is entitled to notice apart from the beneficiaries named in the trust.  Nobody is automatically entitled to discovery and nobody is automatically entitled to object.  While a disgruntled family member can always file a lawsuit against a trust, they face an entirely different procedure, with significant obstacles in their path.

Conclusion

For all these reasons, a Medicaid Asset Protection Trust is a compelling strategy.  It is extremely reliable and widely accepted as the “gold standard” in Elder Law planning.  Learning more by having a consultation with an Elder Law attorney would be a valuable step in determining whether a MAPT is appropriate for you.
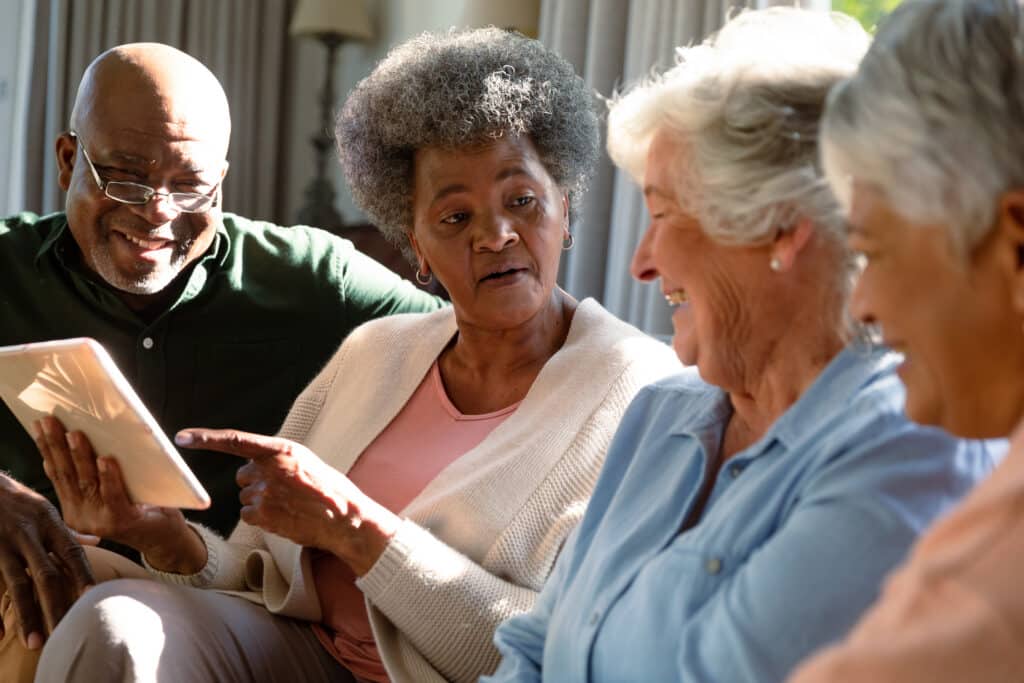
FREE In-Person CEU October 15

Sign Up Now for the October 15 CEU at Broadview at Purchase College

Need to review the flyer? Click here

Register for Oct 15 CEU Course at Broadview Senior Living

Contact Details

Name(Required)
Professional Designation(Required)